The Bank of Canada raised interest rates this week. Before you make an extra mortgage payment, there’s something worth checking.
On October 28, the Bank of Canada raised its policy rate by 0.25 percentage points to 2.5%.
If you have a variable-rate mortgage or line of credit, borrowing may now cost you more.
But here’s something that is easy to overlook:
Not all interest costs you the same amount after tax.
And that can make a big difference when deciding which debt to pay off first.
Let’s look at two loans.
Imagine you have:
- A $500,000 mortgage on your family home.
- A $500,000 line of credit you used to purchase a rental property.
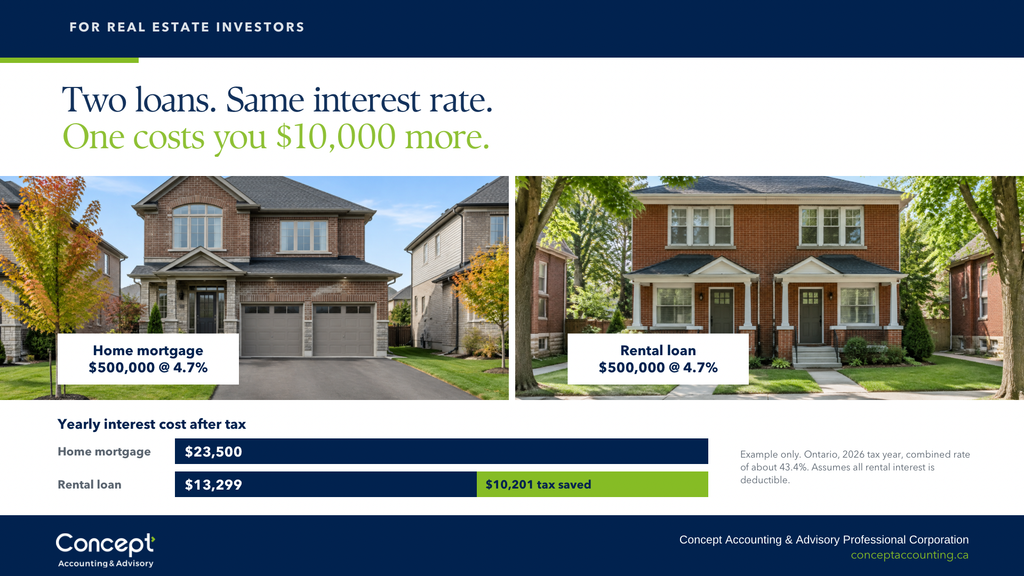
Both have the same interest rate: 4.7%.
Both cost you $23,500 a year in interest.
You might assume they’re equally expensive.
They’re not.
The interest on your home mortgage is generally not tax-deductible. You pay the full $23,500 out of your pocket.
But the interest on the money borrowed to purchase your rental property is generally deductible against your rental income.
That deduction can save you thousands in taxes.
Here’s what that looks like for someone living in Ontario with 2026 taxable income between $117,045 and $150,000. In that range, the combined federal and Ontario tax rate is about 43.4%.

That’s a difference of more than $10,000 a year.
Same loan balance. Same interest rate.
Very different cost after tax.
This is a simplified illustration. It assumes the full rental interest is deductible and saves tax at 43.4%. Actual savings depend on your situation.
So which loan should you pay off first?
Let’s say you have an extra $20,000 sitting in your bank account.
Should you put it toward your home mortgage or your rental line of credit?
Assuming both loans have the same rate and you can make either repayment without penalties, paying down your home mortgage generally makes more financial sense.
Why?
Because every dollar of interest you avoid on your home mortgage is a dollar saved.
But when you reduce deductible rental interest, you also reduce your tax deduction.
The lesson: Don’t compare interest rates alone. Compare what each loan costs you after tax.
There’s one catch that is easy to miss.
You might think that because a loan is secured against your rental property, its interest is deductible.
That’s not how CRA looks at it.
What matters is what you used the borrowed money for.
For example:
- Borrow against your home to purchase a rental property? The interest may be deductible.
- Borrow against your rental property to renovate your personal home? The interest generally isn’t deductible.
And if you’ve used the same line of credit for both personal and rental expenses, things get more complicated.
You generally can’t make a payment and simply declare that you’ve paid off the personal portion first. CRA requires repayments to reduce both portions proportionately.
That’s one reason I recommend keeping personal and investment borrowing separate wherever possible.
One thing worth doing before year-end
Pull out the statements for your mortgages and lines of credit.
For each loan, ask yourself:
What did I actually use this borrowed money for?
You may discover that you’re missing an interest deduction you’re entitled to claim.
Or that you’re paying down the wrong loan first.
With interest rates now higher, it’s worth reviewing.
The goal isn’t simply to pay less interest. It’s to keep more of your money after tax.
That’s the kind of review I work through with clients: understanding where their debt sits, what it really costs, and where their next dollar can do the most good.
Concept Accounting & Advisory Professional Corporation | conceptaccounting.ca